Credit help for home buyers
Credit repair for buying a house, before the lender looks
The months before you apply are when your credit work pays off most. We help you see what an underwriter will see, fix what is wrong, and walk into the mortgage with a plan.
Why it matters
Your middle score sets your rate
When a mortgage underwriter reviews your credit, they pull Equifax, Experian and TransUnion and use your middle score. Not the highest, not the average. One bureau with an error can be the one that decides your rate, and on a 30-year loan a better rate adds up to real money.
That is why home buyers start with a free three-bureau credit report analysis, not a single score from a card app. It is part of our full credit and debt management services.
The plan
Getting mortgage-ready, step by step
- See all three scoresWe review your merged report and show you which bureau is holding your middle score down.
- Fix what is wrongInaccurate, outdated or unverifiable items are disputed through credit repair, starting with the ones that matter most to a lender.
- Lower your usageBalances relative to limits count for about 30 percent of your score. We plan which balances to pay down first.
- Avoid new damageNo new accounts, no closed cards and no surprise inquiries in the months before you apply.
- Handle collections wiselySome are worth settling, some are better left alone until after closing. We tell you which is which.
- Apply with confidenceWe help you judge when your score is ready, so you apply once and on your terms.
Trusted by lenders
Mortgage professionals send buyers to us
“Don’t let blemished credit keep you from buying your dream home. I always refer homebuyers to Credit Solutions.”
J. Allan HansenPresident, Heritage Lending Corp.
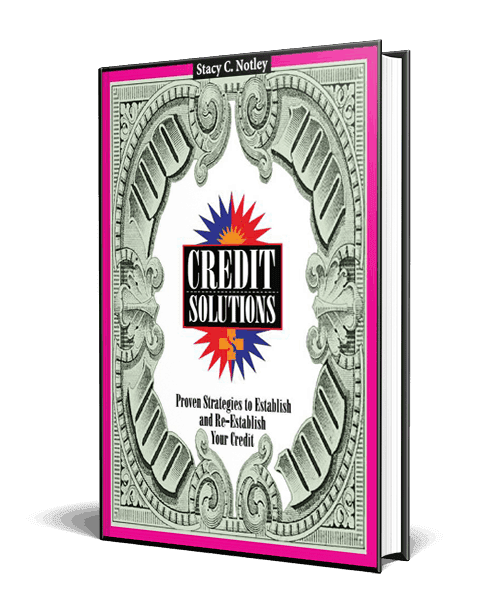
Stacy C. Notley’s book, Credit Solutions, has been recommended by lenders for years. One mortgage loan officer who attended his seminar said it taught him tricks he had no idea existed.
Before you apply
Five mistakes that cost home buyers points
- Opening a new card for the furniture discount. New accounts can lower your score and raise questions.
- Closing old cards. It lowers your available credit and can shorten your credit history.
- Watching only one score. Lenders use your middle score across three bureaus.
- Paying a collection without a plan. How and when you pay it matters.
- Waiting until the application. Disputes take time, so start months ahead.
★★★★★
“We are trying to buy a house and needed help understanding what is on our credit report and how to fix it before we start to purchase a house. They have been very helpful explaining what is needed to improve our score. We have now been working with them for six months and they are still very responsive. This company truly cares and helps you understand how to manage your credit for life!”
Rachel S.Preparing to buy a home
★★★★★
“Since day one Mr. Notley explained the whole process to fix my credit in detail. Him and his whole team have been working on my credit for about 5 months now and my credit is looking way better than it did. His team follows up with you to inform you how everything is going. I highly recommend him! By the way, I have his book and it is very helpful.”
Ana F.Credit repair client
Questions
Credit and buying a home
How long does credit repair take?
It depends on how many items need attention and how the credit bureaus respond. A bureau generally has 30 days to investigate a dispute, and some items take more than one round. Many of our clients work with us for several months. We will tell you what to expect for your own report before you begin.
Will closing a credit card raise my score?
Usually not. Closing a card lowers your available credit, which raises the share you are using, and it can shorten the average age of your accounts. Older accounts show stability.
Which credit score does a mortgage underwriter use?
Your middle score from Equifax, Experian and TransUnion. That is why it matters to know all three, not just the one your bank or card app shows you.
Does my income affect my credit score?
No. Income and occupation are not part of a credit score. Lenders still look at income when they decide how much to lend.
The Manning Group, Inc. · Since 1983
Planning to buy in the next year?
Start now. A free 15-minute call and a three-bureau review will tell you exactly what stands between you and a better rate.
Or call (972) 458-9100 · toll free (888) 458-9100